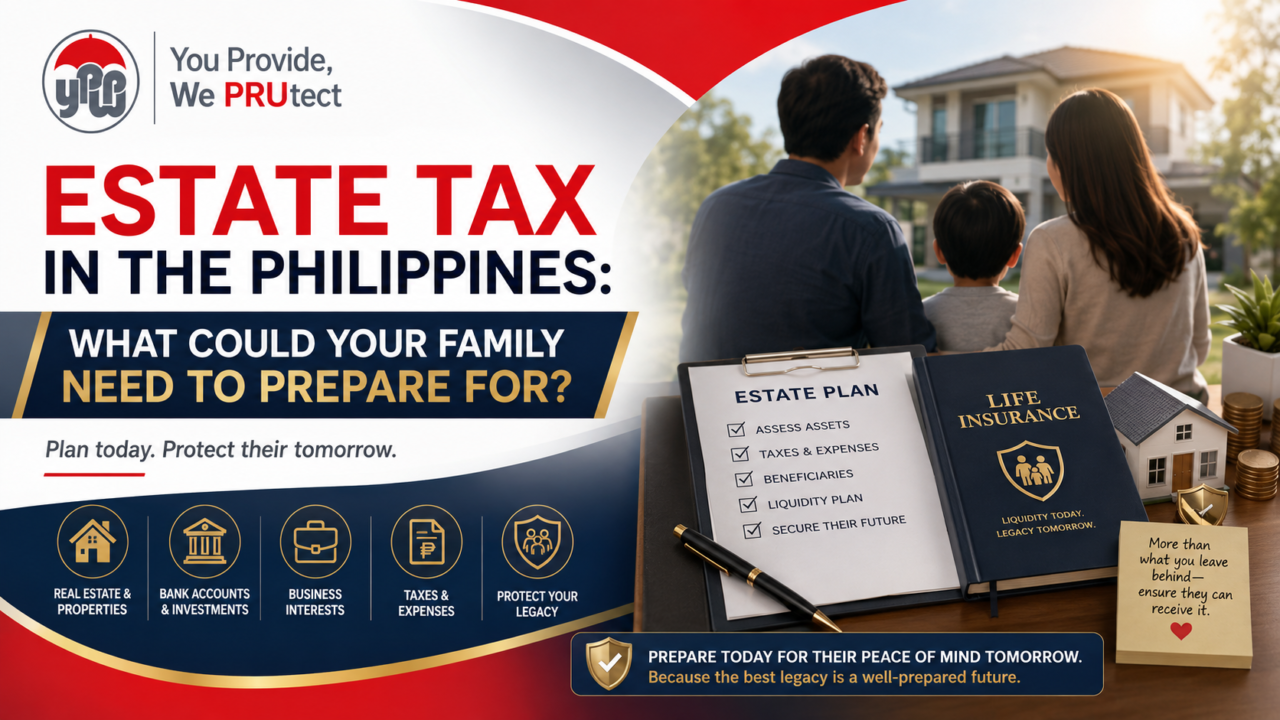
When we talk about leaving something behind for our family, we often think about a house, a lot, savings in the bank, a business, investments, or other assets.
But have you ever wondered:
What happens to these assets when you are no longer around?
Many Filipinos assume that their children or other heirs can simply inherit everything that was left behind. However, transferring an estate can involve taxes, documentation, legal processes, and other settlement expenses.
One of the things families may need to prepare for is estate tax.
This is why estate planning isn’t only for wealthy families. It can be an important part of preparing for the financial future of the people you love.
What Is Estate Planning?
Estate planning is the process of deciding how your assets, financial affairs, and other matters should be handled and transferred to your intended beneficiaries or heirs.
Your estate may include:
- Real estate properties
- Bank savings and deposits
- Investments
- Business interests
- Personal properties
- Other assets and financial interests
Estate planning helps answer important questions such as:
Who should receive my assets?
How should my assets be transferred?
What taxes and expenses may need to be paid?
Where will the money come from to settle these obligations?
Without proper planning, your family may have to figure these things out while they are already dealing with the emotional impact of losing a loved one.
What Is Estate Tax?
In simple terms, estate tax is a tax imposed on the transfer of the net estate of a deceased person to their heirs or beneficiaries.
This is different from an annual property tax or income tax.
The estate tax is associated with the transfer of assets after death.
For example, imagine a parent leaves behind:
- A family home
- A piece of land
- Money in bank accounts
- Investments
- A family business
The family may eventually inherit these assets, but settling the estate isn’t necessarily as simple as signing a document and receiving everything immediately.
There may be estate tax and other costs or requirements that need to be addressed as part of the settlement process.
And this is where many families may be caught unprepared.
“But We Already Have the Property.”
This is one of the misconceptions worth understanding.
Owning an asset and being able to transfer that asset to the next generation are not always the same thing.
A family may own a property for decades, but when the owner passes away, the heirs may still need to go through the proper process to settle and transfer the estate.
If the family doesn’t have enough readily available funds, they may face difficult decisions.
They may need to find money elsewhere.
They may delay the settlement.
And in some situations, families may consider selling or borrowing against an asset to raise the funds needed for estate settlement.
This is why estate planning should not only focus on what you will leave behind.
It should also consider how your family will be able to receive what you leave behind.
Why Is Estate Planning Important?
Estate planning isn’t simply about distributing wealth.
It’s about making the transition easier for your family.
1. It Helps Organize Your Assets
You may know exactly what you own, but will your family know?
Estate planning can help create a clearer picture of your assets, accounts, properties, investments, and other financial interests.
This can make it easier for your family to determine what needs to be settled and transferred.
2. It Helps Prepare for Taxes and Expenses
One of the biggest mistakes families can make is assuming that the value of an estate automatically equals the amount their heirs will receive.
There can be taxes, professional fees, documentation costs, and other expenses associated with settling an estate.
Planning ahead can help your family prepare for these financial obligations.
3. It Can Help Reduce Financial Stress on Your Family
Losing a loved one is already difficult.
Your family shouldn’t have to immediately ask:
“Saan tayo kukuha ng pambayad?”
Having a financial strategy in place can give your family another source of funds when they need it most.
4. It Helps Protect What You Worked For
You worked for your home.
You built your savings.
You invested for the future.
You built your business.
Estate planning helps you think beyond simply accumulating these assets.
It helps you plan how they can be passed on to the people you intend to benefit.
Where Can Life Insurance Fit Into Estate Planning?
This is where life insurance can become an important financial planning tool.
A life insurance policy can provide a death benefit to the policy’s beneficiaries when the insured person dies, subject to the policy’s terms and conditions.
That benefit can potentially provide your family with liquidity — money that can be used for immediate financial needs.
And liquidity can be particularly important when an estate consists largely of assets that aren’t easily converted into cash.
Think about a family home.
A house may be worth millions of pesos, but you cannot simply withdraw part of its value from the property to pay an immediate obligation.
The same can be true for land or other long-term assets.
Life insurance can provide a source of cash that may help your family address financial obligations without immediately having to sell important assets.
For example:
Imagine a parent leaves behind:
₱10 million in properties
but only has
₱200,000 in readily available cash.
The family may have significant wealth on paper, but that doesn’t necessarily mean they have enough liquid funds available when expenses arise.
Now consider a properly structured life insurance policy that provides a death benefit.
The death benefit may provide the family with additional liquidity that can be used, depending on the circumstances and applicable rules, to help address estate-related obligations and other financial needs.
The goal isn’t necessarily to replace the assets.
It’s to help provide the cash needed so the family doesn’t have to immediately sacrifice those assets.
Life Insurance Isn’t Just About Leaving Money Behind
When people hear “life insurance,” they often think:
“Para lang ‘yan kapag namatay.”
But from a financial planning perspective, life insurance can serve a bigger purpose.
It can be part of a strategy for protecting the financial value you have accumulated and preparing for the eventual transfer of your wealth.
For example, someone may spend decades building:
- A family home
- Several properties
- Savings
- Investments
- A business
Estate planning asks:
“How can I make sure these assets can be passed on as smoothly as possible?”
Life insurance can address another important question:
“Where can my family get liquidity when they need cash after I’m gone?”
These are two different questions — but they can work together as part of a comprehensive financial plan.
A Simple Way to Think About Estate Planning
You can think of estate planning as having three parts:
1. WHAT will you leave behind?
Your properties, savings, investments, business, and other assets.
2. WHO should receive them?
Your intended heirs or beneficiaries, based on your estate plan and applicable Philippine laws.
3. HOW will your family settle and transfer them?
This is where taxes, documentation, settlement costs, and liquidity become important.
Many people focus heavily on the first two.
But the third question is often overlooked.
Start Planning Before Your Family Needs To
Estate planning isn’t only for the ultra-wealthy.
Even if your estate consists of one house, a bank account, some investments, or a small business, it’s worth understanding what could happen to those assets when they are eventually transferred to your heirs.
You don’t have to wait until you have millions of pesos in assets before you start thinking about it.
In fact, planning earlier gives you more time to:
- Understand your assets
- Organize your financial documents
- Learn about estate tax and applicable exemptions or deductions
- Determine who you intend to benefit
- Discuss your plans with your family
- Consult the appropriate legal and tax professionals
- Consider financial tools such as life insurance that may provide liquidity
And most importantly, you can make these decisions while you’re still here to make them.
Your Legacy Is More Than What You Leave Behind
Building wealth is only one part of financial planning.
Protecting and transferring that wealth is another.
You may spend your entire life building assets for your family. But without proper planning, your heirs may face financial and administrative challenges when it is time to settle your estate.
Estate tax is just one of the considerations.
The bigger question is:
“Have I prepared my family for what happens to everything I’ve worked hard to build?”
Life insurance may be one of the tools you can consider as part of that preparation — particularly when your family may need liquidity to help settle financial obligations while preserving the assets you worked hard to accumulate.
Because leaving a legacy isn’t just about how much you leave behind.
It’s also about making sure your family is prepared to receive it.
Important: Estate tax rules, exemptions, deductions, filing requirements, and other regulations can change and may depend on the specific circumstances of an estate. Life insurance proceeds may also have different tax and legal treatment depending on the policy structure, ownership, beneficiaries, and applicable Philippine laws. For estate-specific advice, consult a qualified tax or legal professional.
Planning today can help make tomorrow easier for the people you love.