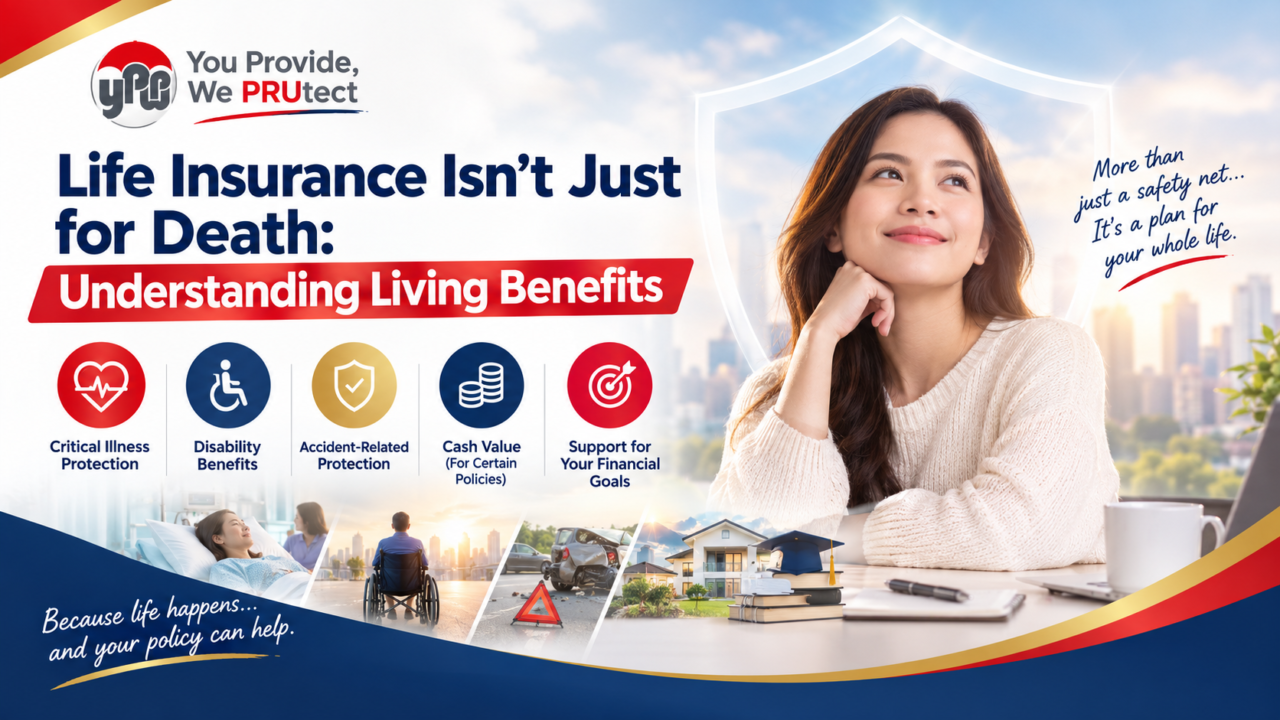
When people hear the words life insurance, one of the first things that often comes to mind is the death benefit—the financial protection provided to loved ones when the insured person passes away.
And that protection is important.
But here’s something many people may not realize:
Your life insurance policy may also provide benefits that you can use while you’re still alive.
Depending on the policy and the riders attached to it, life insurance can provide financial support not only when life ends, but also when unexpected events happen during your lifetime.
These are commonly referred to as living benefits.
What Are Living Benefits?
Living benefits are benefits provided by certain life insurance policies or riders that can help the policyholder financially while they are still living.
Instead of receiving benefits only after death, you may have access to financial protection when you experience certain situations covered by your policy.
These may include events such as:
- Being diagnosed with a covered critical illness
- Becoming totally and permanently disabled
- Experiencing an accident covered by the policy
- Needing financial support during a serious health event
- Reaching certain milestones or conditions specified in the policy
The exact benefits depend on the type of policy, the riders attached to it, the definitions of covered conditions, and the terms and conditions of the contract.
That’s why it’s important to understand not just how much life insurance coverage you have, but also what your policy can potentially do for you while you’re alive.
1. Critical Illness Protection
One of the most commonly discussed living benefits is protection against critical illnesses.
A serious illness can create two financial problems at the same time.
First, there may be significant medical and treatment expenses.
Second, your ability to earn income may be affected while you focus on recovery.
Even if you have health insurance or government benefits, there can still be other expenses to consider—such as medications, transportation, rehabilitation, household expenses, or income lost during recovery.
A life insurance policy with an appropriate critical illness benefit or rider may provide a lump-sum benefit when a covered critical illness is diagnosed, subject to the policy’s conditions.
This money may help you manage expenses and maintain financial stability while you recover.
The goal isn’t to replace your health insurance.
Instead, it can provide another layer of financial protection.
2. Disability Benefits
What happens if an illness or accident prevents you from working?
For many people, this can be just as financially damaging as a major medical expense.
If your income stops or is significantly reduced, your regular financial responsibilities don’t necessarily stop with it.
You may still have:
- Household expenses
- Loan payments
- Insurance premiums
- Utility bills
- Family responsibilities
- Savings goals
- Education expenses
Some life insurance policies may include disability-related benefits or riders designed to provide financial support if you become disabled according to the policy’s definition.
This can help protect not only your future income, but also the financial plans you’ve been working toward.
3. Accident-Related Protection
Accidents can happen without warning.
A serious accident can result in hospitalization, disability, loss of income, or even death.
Depending on your coverage, your life insurance policy may include accident-related benefits that provide additional financial protection.
For example, certain policies may provide benefits for accidental death or specific accidental injuries, subject to the policy terms.
This can provide an additional layer of protection on top of your basic life insurance coverage.
4. Your Policy May Help During Major Life Events
Living benefits aren’t limited to health-related situations.
Some life insurance policies can also provide financial value during your lifetime through features such as cash values, depending on the type of policy.
Certain permanent life insurance policies may accumulate cash value over time.
That value may potentially be accessed or used according to the policy’s provisions.
However, this is an area where it’s especially important to understand the difference between guaranteed values, non-guaranteed values, withdrawals, and policy loans.
Accessing policy values can also affect your coverage, cash value, and future benefits.
This is why your policy should be viewed as a financial contract—not simply as a savings account.
5. Living Benefits Can Protect Your Financial Plans
Think about the financial goals you’re currently working toward.
Maybe you’re building an emergency fund.
Maybe you’re saving for a home.
Maybe you’re paying off debt.
Maybe you’re investing for retirement.
Or maybe you’re helping your family financially.
Now imagine that a serious illness or disability suddenly interrupts your ability to earn.
The problem isn’t necessarily that your financial goals disappear.
The problem is that your ability to fund those goals may suddenly change.
This is where living benefits can play an important role.
They can provide financial support during certain difficult situations, helping you avoid completely derailing the plans you’ve worked hard to build.
Life Insurance Can Protect More Than Your Family
Traditionally, life insurance is often presented as a way to protect your family financially after you’re gone.
And that’s still one of its most important purposes.
But your financial life doesn’t begin and end with your death.
You can experience illness.
You can experience disability.
You can experience accidents.
You can experience unexpected financial challenges.
Living benefits recognize that financial protection may also be needed while you’re still here.
That’s why choosing life insurance shouldn’t be based solely on the question:
“How much will my family receive if I die?”
It’s also worth asking:
“What can this policy do for me while I’m alive?”
Not All Life Insurance Policies Have the Same Living Benefits
This is an important distinction.
Not every life insurance policy provides the same living benefits.
Some policies may include certain benefits automatically, while others may require additional riders. Some benefits may only apply when specific conditions are met.
The amount of coverage, eligibility requirements, covered illnesses or events, waiting periods, exclusions, and claim requirements can also vary.
That’s why you shouldn’t assume that another person’s policy has the same benefits as yours.
Your policy contract is the best source for determining exactly what you’re covered for.
If you’re unsure, consider reviewing your policy with your financial advisor.
Ask questions such as:
- What living benefits are included in my policy?
- Do I have critical illness coverage?
- Do I have disability-related protection?
- What conditions or events are covered?
- How much benefit could I receive?
- What are the requirements for making a claim?
- Are there exclusions or waiting periods?
- Do I have riders that I may have forgotten about?
You may be surprised by what your policy actually provides.
The Bottom Line
Life insurance isn’t necessarily just about preparing for death.
It’s about preparing for life—including the unexpected things that can happen along the way.
A well-designed life insurance plan can provide financial protection for your loved ones if you pass away, while certain benefits and riders may also provide financial support if you experience serious health conditions, disability, accidents, or other covered events during your lifetime.
The key is understanding your coverage before you need it.
Because the best time to discover what your policy can do for you is before something happens—not after.
So take a moment to review your life insurance policy.
Don’t just ask:
“How much will my family receive when I’m gone?”
Also ask:
“What can my policy do for me while I’m still here?”
That question could change the way you look at life insurance.