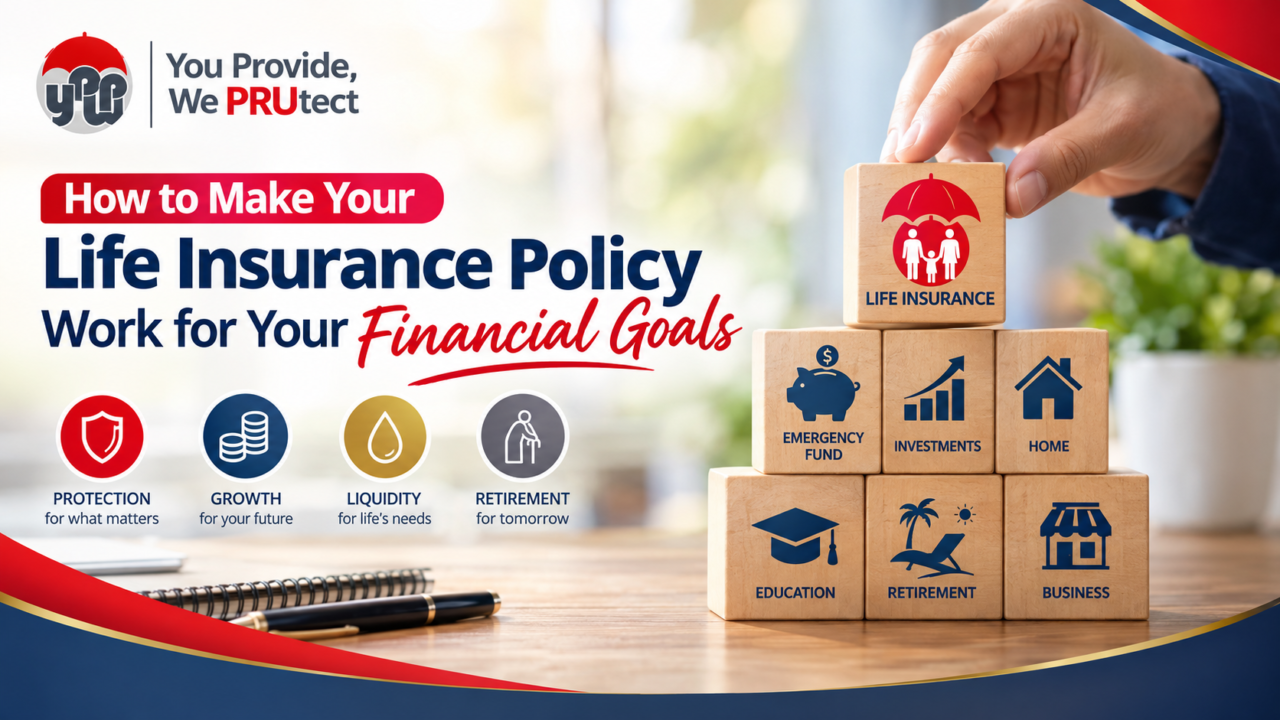
Main Question: How can I make my life insurance work together with my other financial goals?
When people think about financial planning, they often separate everything into different boxes: savings for emergencies, investments for wealth building, insurance for protection, and retirement funds for the future.
But good financial planning isn’t necessarily about choosing one over the other. It’s about making sure each part of your financial plan has a purpose—and that those parts work together.
Your life insurance policy can be one of those pieces.
Instead of asking, “Should I choose insurance or investing?”, a better question may be:
“How can I use life insurance alongside my other financial tools to help protect and pursue my financial goals?”
Let’s take a closer look.
1. Start With Your Financial Goals
Before choosing a policy or deciding how much coverage you need, identify what you’re actually trying to accomplish financially.
Your goals might include:
- Building an emergency fund
- Protecting your family’s financial security
- Buying a home
- Preparing for your children’s education
- Growing your investments
- Preparing for retirement
- Starting a business
- Creating additional financial resources for the future
Each goal may require a different financial strategy.
For example, an emergency fund is designed for accessibility and short-term needs, while investments may be intended for long-term growth. Life insurance, on the other hand, primarily provides financial protection against risks that could significantly affect you or your loved ones.
Understanding the purpose of each financial tool helps you avoid expecting one product to do everything.
2. Use Life Insurance to Protect the Financial Plan You’re Building
Imagine spending years building your savings and investments, only for an unexpected event to create a large financial burden for your family.
This is where life insurance can play an important role.
A life insurance policy can provide a death benefit to your beneficiaries if you pass away while the policy is in force. This can help provide financial support and potentially protect the plans you’ve been working toward.
For example, if you’re building a retirement fund, buying a home, or supporting your family’s future, life insurance can help reduce the financial impact your family may face if you are no longer around to contribute.
In this way, insurance doesn’t necessarily replace your financial goals—it can help protect them.
3. Build Your Emergency Fund Separately
An emergency fund and life insurance serve different purposes.
Your emergency fund is designed to help you handle unexpected expenses while you’re alive—such as job loss, urgent repairs, or other financial emergencies.
Life insurance, depending on the policy and its features, is primarily designed to provide protection against specific risks covered by the policy.
That’s why having both can be valuable.
A practical approach may be:
Emergency fund → handles financial emergencies
Life insurance → provides financial protection against covered risks
Investments → pursue long-term growth
Retirement savings → prepare for future income needs
The goal isn’t to make one financial product responsible for everything.
4. Consider the Role of Your Policy’s Financial Value
Some types of life insurance policies may accumulate cash or policy value over time, depending on the product, policy structure, premiums paid, and applicable charges.
This financial value can potentially give the policy another dimension beyond its death benefit.
However, it’s important to understand that policy value is not the same thing as a traditional investment account.
The amount and availability of any cash value depend on the specific policy. Accessing it may also affect the policy’s benefits and future sustainability.
That’s why policyholders should understand how their particular policy works before treating its value as part of their financial strategy.
5. Don’t Forget Living Benefits
Life insurance doesn’t necessarily have to be viewed only in terms of what happens after death.
Depending on the policy and riders attached to it, some life insurance plans may provide benefits that can be used while you’re alive—for example, coverage related to certain critical illnesses, disability, or other qualifying events.
These features can provide another layer of financial protection.
Think of it this way:
Your financial plan prepares you for the future you hope to have—and protection helps prepare you for the unexpected events that could change that future.
That’s an important distinction.
6. Make Sure Your Coverage Matches Your Responsibilities
Your financial needs can change as your life changes.
When you’re young and just starting your career, you may have fewer financial responsibilities. As your income grows, however, you may eventually take on a mortgage, start a family, support your parents, or accumulate other financial commitments.
Your life insurance coverage should be reviewed as these responsibilities change.
Ask yourself:
- Has my income increased significantly?
- Have I taken on new debts?
- Do I have people who depend on my income?
- Have I purchased a home?
- Have I started a business?
- Have my financial goals changed?
- Has my existing coverage kept up with my responsibilities?
A policy that was appropriate several years ago may not necessarily provide the same level of protection today.
7. Don’t Sacrifice Your Other Financial Priorities
One common mistake is trying to put too much money into one area of financial planning.
For example, someone might focus heavily on insurance while neglecting their emergency fund. Another person might invest aggressively while having little protection against financial risks.
A balanced approach considers both protection and growth.
Your financial plan may include:
Protection
Life insurance and appropriate health-related or other insurance coverage
Liquidity
Emergency savings and accessible funds
Growth
Investments designed for your long-term goals
Future planning
Retirement and other long-term financial objectives
The right balance depends on your income, responsibilities, risk tolerance, goals, and stage of life.
8. Review Your Policy as Part of Your Overall Financial Plan
Getting a life insurance policy shouldn’t necessarily be the end of the conversation.
Your financial situation can change over time, so your policy should be reviewed alongside your broader financial plan.
A regular review can help you determine whether:
- Your coverage is still appropriate
- Your beneficiaries are updated
- Your premiums remain manageable
- Your policy’s features still match your needs
- Your financial goals have changed
- Your policy is working alongside your savings and investments
Think of your financial plan as something that evolves with you.
Your insurance should evolve with it when appropriate.
9. Don’t Think of Financial Planning as “Insurance vs. Investment”
One of the biggest misconceptions about financial planning is that you have to choose between insurance and investments.
They can serve different purposes.
Insurance is primarily about protection.
Investing is primarily about pursuing growth.
Savings provide liquidity.
Retirement accounts help prepare for future income needs.
Each financial tool can have a different role.
The question isn’t always which one is better. The more useful question is:
What role does each one play in my financial plan?
When you understand those roles, you can make decisions based on your actual goals rather than simply comparing products.
10. Let Your Financial Goals Guide Your Policy Decisions
Ultimately, your life insurance policy should be connected to your financial priorities.
If your main concern is protecting your family, your coverage may need to focus on adequate protection.
If you’re building long-term financial resources, you may want to understand whether a particular policy has features that complement your broader plan.
If you’re concerned about unexpected health events, you may want to explore whether your policy offers relevant living benefits or riders.
There is no single life insurance strategy that works for everyone.
The right approach depends on your circumstances.
The Bigger Picture: Make Every Financial Tool Have a Purpose
Life insurance doesn’t have to work alone.
It can work alongside your emergency fund, savings, investments, retirement planning, and other financial strategies.
The key is understanding what each part of your financial plan is designed to accomplish.
Think of it like building a house.
Your investments may help you build wealth.
Your savings can provide liquidity.
Your retirement plan can help prepare you for the future.
And your insurance can help protect the people and financial goals that matter to you from certain unexpected risks.
The goal isn’t simply to own a life insurance policy. The goal is to make sure your policy has a meaningful place in your overall financial plan.
A Simple Financial Planning Checklist
Take a moment to ask yourself:
☐ What are my top three financial goals?
☐ How much emergency savings do I have?
☐ Who depends on my income?
☐ How much life insurance coverage do I currently have?
☐ Does my coverage match my current responsibilities?
☐ Does my policy have living benefits or other features I should understand?
☐ Am I saving and investing for my long-term goals?
☐ When was the last time I reviewed my policy?
If you can’t confidently answer some of these questions, it may be a good time to review your overall financial plan.
Final Thoughts
Life insurance is just one piece of the financial puzzle.
It doesn’t have to replace your savings. It doesn’t necessarily have to replace your investments. And it shouldn’t be expected to accomplish every financial goal on its own.
Instead, think about how it can complement the other strategies you’re already using.
Your financial goals are unique to you. Your insurance strategy should be designed with those goals, responsibilities, and priorities in mind.
Because ultimately, financial planning isn’t about having the most financial products.
It’s about having the right protection and resources working together toward the future you want.
Ready to see where life insurance fits into your financial plan?
A financial review can help you understand your existing coverage, identify potential gaps, and see how your policy can work alongside your other financial goals.